Vass International is the only member of SBC Global Alliance in UAE. We are located at Karama, Dubai and provide professional services to our clients across the region.
- Zainal Mohebi Plaza, Karama, Dubai, UAE
- +971 50 210 5100
- info@vassintl.com
- vassintl.com
Internal Audit & Risk Consulting
INTERNAL AUDIT & RISK MANAGEMENT
Identify the Risks. Strengthen What Matters.
VASS International helps businesses
identify operational and financial
control gaps, evaluate risk exposure
and develop practical improvement
recommendations.
Our internal audit and risk management
services in Dubai and across the UAE
focus on clearer accountability,
stronger processes and better
management oversight.
✓
Risk-Based Audit Planning
✓
Internal Controls Review
✓
Practical Risk Findings
✓
Management Action Plans
Scope, deliverables and timelines are agreed for each engagement.
VASS INTERNATIONAL
Risk Intelligence Workspace
IA / 01
Select the area you want to review
FINANCIAL REVIEW
Financial Controls
Review approval workflows, reconciliations and reporting controls.
Potential Review Outputs
Illustrative
- Transaction approval review
- Reconciliation observations
- Segregation-of-duties assessment
Discuss your selected
review scope with VASS.
Discuss This Area ↗
Scope •
Assess •
Test •
Report •
Follow Up
WHAT WE REVIEW
Internal Audit Services, Built Around Your Risks.
Every organisation has different processes and exposures. Select an audit service to explore its potential scope and deliverables.
Select an Audit Service
06 service areas
VASS / AUDIT CAPABILITIES
01 / 06
Risk-Based Internal Audit
A structured internal audit approach that prioritises business risks, relevant controls and important operating processes.
Potential Deliverables
Scope dependent
- Risk-based audit plan
- Control-testing observations
- Prioritised findings report
Discuss your audit requirements, reporting period and intended outcomes.
Discuss This Service ↗The descriptions and outputs above are illustrative. Engagement scope, reporting, independence and deliverables are confirmed before an assignment begins.
Request a Consultation ↗UNDERSTAND YOUR RISK EXPOSURE
Every Risk Has a Position. Know What to Prioritise.
Explore how likelihood and potential business impact can influence risk prioritisation. Select any cell or example scenario to see an illustrative assessment.
Risk Assessment Matrix
5 × 5 FRAMEWORK
5
4
3
2
1
1
2
3
4
5
Likelihood ↑
Impact →
Low
Moderate
High
Critical
All scores are illustrative. The 1–25 thresholds are a demonstration model, not a universal audit standard or an assessment of your business.
Risk Prioritisation Explorer
IA / 03
12
OUT OF 25
High Risk
Likelihood: 3 / 5
Impact: 4 / 5
INDICATIVE RESPONSE
Prioritised Management Review
Review relevant controls, assign responsibility and agree a proportionate improvement plan.
Need a risk assessment tailored to your organisation?
Discuss Risk Assessment ↗Risk scoring methodologies, appetite thresholds and management actions should be tailored to each organisation. A risk matrix is a prioritisation aid, not a substitute for professional judgment.
Request a Consultation ↗INTERNAL CONTROL EFFECTIVENESS
Behind Every Business Process, There Are Controls to Review.
Select a business function, then explore specific control checkpoints. Understand how VASS can structure a review around the processes that matter to your organisation.
CONTROL REVIEW WORKSPACE
IA / 04
Finance Controls
Review payment approvals, reconciliations and financial reporting controls.
Explore Control Checkpoints
Select a step
SELECTED CONTROL CHECKPOINT
Payment Authorisation
Review approval limits, authorisation responsibilities and evidence supporting relevant transactions.
REVIEW OBJECTIVES
From Control Design to Practical Improvements.
VASS can examine how selected controls are designed, who owns them and what evidence exists to demonstrate their operation.
EXAMPLE CONTROL EXPOSURE
Unapproved transactions or incomplete reconciliations.
Potential Review Deliverables
Process and control mapping
Design and operating observations
Financial controls findings
and action plan
Discuss this business process
with VASS International.
Discuss This Review ↗
The examples above illustrate possible review activities and potential control exposures. They are not findings about any particular organisation. The final scope and deliverables are established during engagement planning.
Request a Consultation ↗A CLEAR, STRUCTURED ENGAGEMENT
From Initial Assessment to Actionable Outcomes.
Explore our typical five-stage internal audit process. Each stage is designed to support clear communication, documented work and practical recommendations.
STAGE 01 / 05
Scope & Engagement Planning
Understand business operations, agree audit objectives, identify key stakeholders and establish a clear engagement scope.
Key Activities- Initial discussion and information requests
- Business context and process review
- Engagement scope and timeline
EXPECTED STAGE OUTPUT
DELIVERABLE / 01
Agreed Engagement Scope
Defined objectives, review areas, initial information requirements and an agreed work programme.
Have Questions About the Audit Process?
Discuss Your Audit Scope ↗
Discuss your organisation's requirements, expected scope and audit objectives with VASS International.
This is an illustrative engagement workflow, not a representation of work already performed. Actual procedures, stages, reporting responsibilities and timing depend on the agreed audit engagement.
AUDIT REPORTING & DELIVERABLES
Findings That Lead to Better Decisions.
Clear reporting helps management understand where attention is needed, what actions are recommended and who should take ownership.
VASS / REPORTING FRAMEWORK
Internal Audit Report
Illustrative report extract
OBSERVATION 01 / FINANCIAL CONTROLS
Payment Authorisation Controls
Illustrative High PriorityIn this fictional example, payment approval evidence is insufficient for selected transactions, potentially weakening financial oversight.
RECOMMENDED MANAGEMENT ACTION
Formalise approval thresholds,
document authorisation and
introduce independent review.
Suggested accountable role: Finance Manager. Actual ownership, priority and deadlines are determined by management.
WHAT YOUR ENGAGEMENT MAY INCLUDE
Clear Records. Accountable Actions.
Engagement-specific reporting helps translate observations into structured improvement opportunities.
01
Risk Register
Identified risks, priorities, responsibilities and potential responses.
02
Internal Audit Findings
Evidence-based observations, implications and recommendations.
03
Management Action Plan
Agreed corrective actions, accountable owners and target dates.
04
Discuss Your Audit Requirements ↗
Follow-Up Tracker
Remediation progress, evidence reviewed and outstanding items.
The report extract is fictional and provided solely to illustrate a possible reporting format. Actual findings and deliverables depend on the agreed audit scope.
WHY VASS INTERNATIONAL
An Audit Should Do More Than Identify Problems.
An effective internal audit engagement
helps management see the bigger picture:
where controls need attention, why
weaknesses matter and how improvements
can be prioritised.
At VASS International, our approach
focuses on understanding business
processes, conducting agreed review
procedures and communicating
observations in a clear,
decision-useful format.
The value of an audit lies not only in the findings, but also in what management can do with them.
OUR ENGAGEMENT APPROACH
Clarity in the Findings. Purpose in the Recommendations.
01
Business-Focused Scope
Review objectives aligned with relevant operational risks, processes and management priorities.
02
Evidence-Led Observations
Findings developed through the agreed examination of records, control procedures and available evidence.
03
Practical Recommendations
Clearly described improvement options that management can evaluate, prioritise and assign for action.
04
Clear Communication
Understandable reporting, discussion of findings and defined expectations for agreed follow-up work.
Need an Internal Audit Partner?
Start a Conversation ↗
Tell us about your business, review priorities and proposed engagement scope.
FREQUENTLY ASKED QUESTIONS
Common Questions. Clear Answers.
Planning an internal audit or reviewing your business risk management approach? Here are answers to common questions from organisations considering an engagement.
Need Advice for Your Business?
Discuss your organisation's objectives and proposed audit scope with VASS International.
Contact Our Team ↗What is an internal audit?
An internal audit is an independent, objective assurance and advisory activity that evaluates selected risks, internal controls and governance processes. Its purpose is to provide useful insights and recommendations to support organisational improvement.
What is the difference between internal and external audit?
Internal audit generally evaluates risks, internal controls, governance and business processes. An external financial statement audit primarily provides an independent opinion on financial statements under applicable auditing requirements.
How often should a company conduct internal audits?
The frequency depends on the organisation's risk exposure, operational complexity, applicable requirements and management priorities. Higher-risk functions may need more frequent review than lower-risk processes.
What documents are needed for an internal audit?
Depending on the engagement, documents may include policies, operating procedures, organisation charts, accounting records, management reports, contracts, approval matrices, system access listings and supporting transaction evidence.
How long does an internal audit engagement take?
The timeline varies according to the agreed scope, number of processes or locations, complexity of controls, available documentation and required testing. A proposed schedule can be discussed during engagement planning.
Is internal audit mandatory for every company in the UAE?
Not all UAE businesses are subject to identical internal audit requirements. Obligations can depend on the industry, corporate structure, regulatory framework and applicable governance rules. Organisations should verify requirements relevant to their circumstances.
What deliverables can management expect after an audit?
Depending on the agreed scope, deliverables may include an internal audit findings report, risk register, control observations, recommendations and a management action plan. Follow-up reports may also be included where agreed.
Can VASS help with audit findings follow-up?
Follow-up support can be discussed as part of the engagement scope. This may involve reviewing management actions, examining available implementation evidence and documenting outstanding remediation matters.
VASS INTERNATIONAL / INTERNAL AUDIT ADVISORY
Better Controls Start with a Clearer Understanding of Risk.
Discuss your internal audit objectives, business processes and risk management requirements with VASS International. Let's identify an appropriate review scope for your organisation.
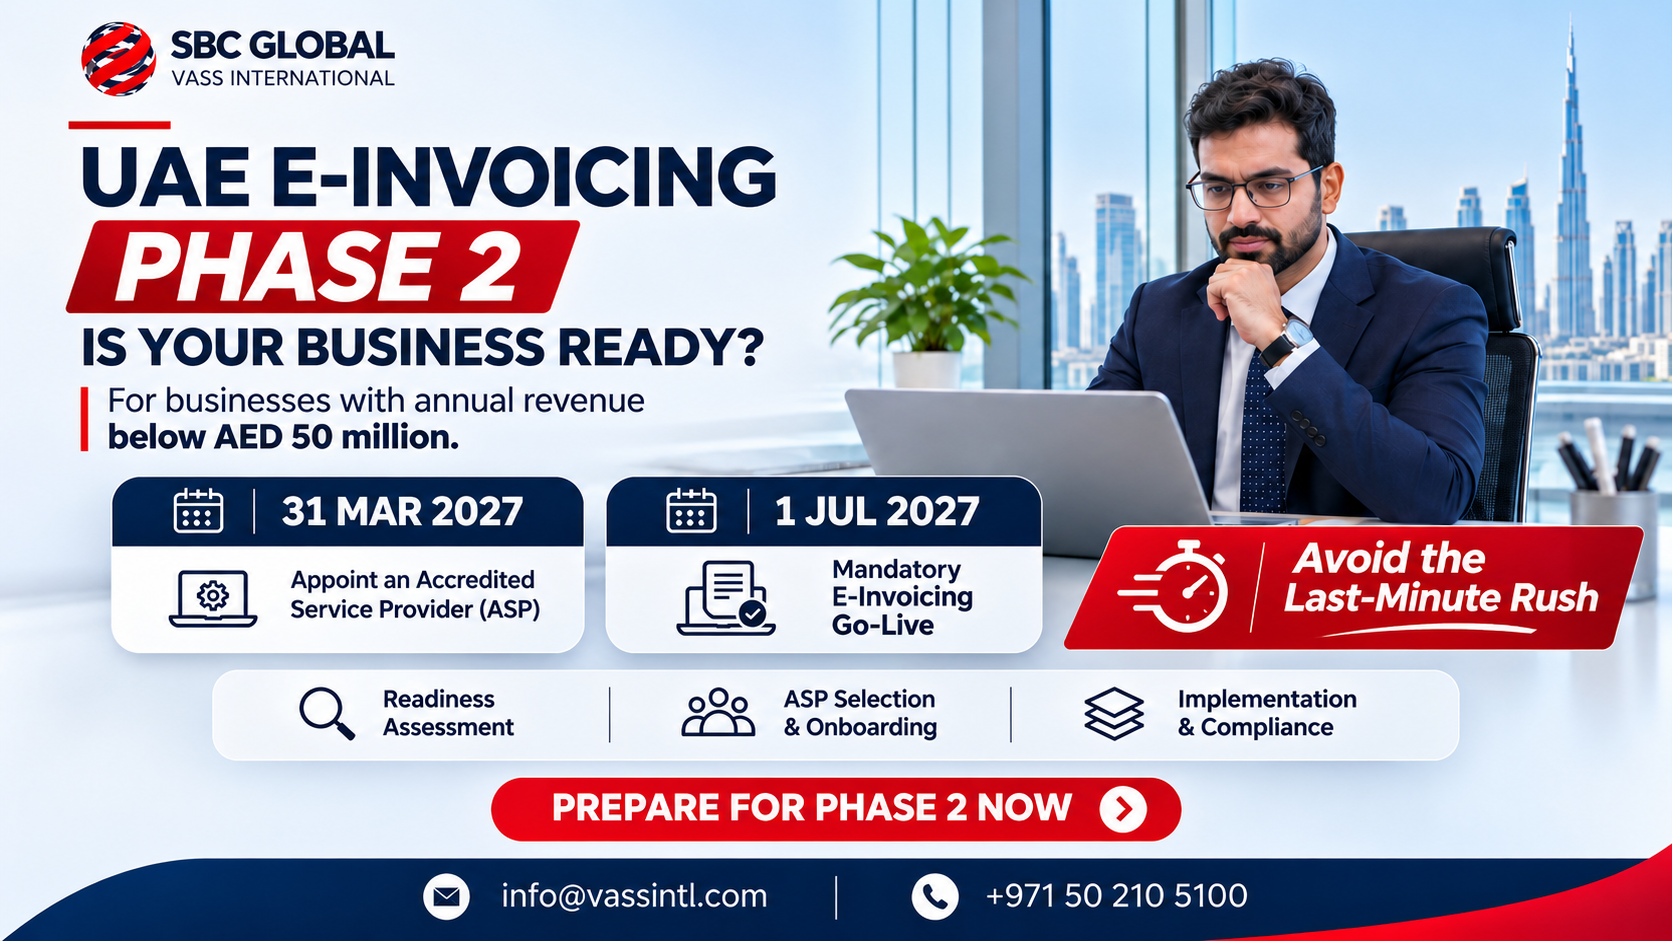
UAE E-INVOICING · PHASE 2
Get Your E-Invoicing Readiness Plan
Submit your details for a consultation with VASS International.
We use your information to respond to your enquiry. Privacy Policy