Estimated reading time: 4 min · Updated November 16, 2026
A reliable UAE VAT tax invoice checklist helps finance teams catch missing details before an invoice reaches a customer or enters the purchase ledger. The correct checks depend on whether the transaction requires a full tax invoice or qualifies for a simplified one. This practical guide explains the distinction, gives an accounts-payable review process and separates ordinary VAT invoice requirements from the emerging structured e-invoicing system.
UAE VAT tax invoice checklist: start with the invoice type
Under the FTA’s published tax-invoice guidance, a simplified tax invoice may be used where the customer is not VAT-registered, or where the customer is VAT-registered and the consideration does not exceed AED 10,000. Otherwise, assess the requirements for a full tax invoice. These are eligibility conditions, not an instruction to issue simplified invoices in every eligible case. See the FTA Taxable Person Guide and FTA tax-invoice explainer.
Full tax invoice: details to check
Use this as an operational review list, alongside the applicable VAT legislation and executive regulation:
- Prominently display “Tax Invoice”.
- Show the supplier’s name, address and Tax Registration Number (TRN).
- Where the recipient is VAT-registered, include the recipient’s name, address and TRN.
- Use a sequential or unique invoice number and state the issue date.
- State the supply date if it differs from the invoice date.
- Identify the goods or services and show relevant quantities, unit prices, VAT rates, line values and discounts.
- Show totals and tax amounts in AED as required, including the applicable exchange-rate information where invoicing in a foreign currency.
- Where the recipient must account for VAT under an applicable reverse-charge arrangement, include the required statement and legal reference.
Some fields depend on the transaction and the current legal provisions. The FTA’s Tax Invoices clarification also explains line-item values, foreign-currency conversion and rounding. Do not use a generic invoice template as a substitute for transaction-specific tax treatment.
Simplified invoice: shorter does not mean incomplete
The FTA lists minimum simplified-invoice particulars: the words “Tax Invoice”; supplier name, address and TRN; issue date; a sufficient description of the goods or services; and total consideration and VAT charged. A normal receipt missing these particulars is not automatically a compliant simplified tax invoice.
Practical three-stage invoice review
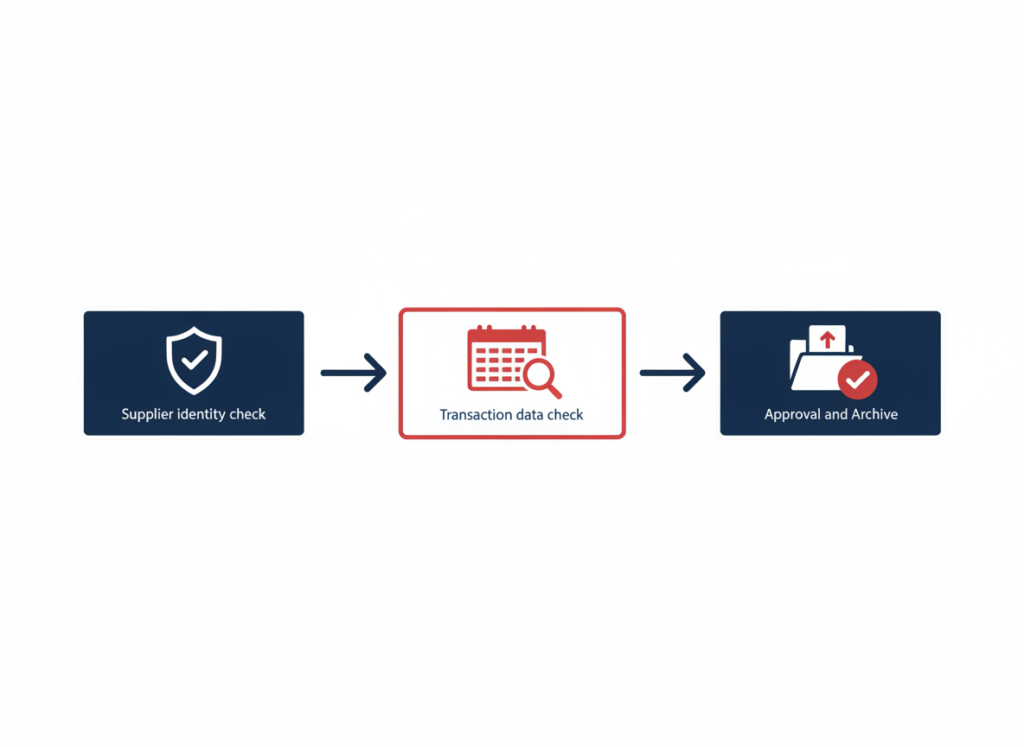
1. Verify supplier and recipient identity
Match the supplier’s legal name and TRN against the supplier master record. For full invoices to VAT-registered customers, check recipient particulars as well. Escalate mismatches rather than silently changing supplier-issued invoices.
2. Reconcile transaction and VAT treatment
Compare the purchase order, contract or delivery evidence with the invoice. Check whether the supply is standard-rated, zero-rated, exempt or subject to another treatment; the correct classification cannot be inferred from the invoice appearance alone. Recalculate VAT and confirm any currency conversion.
3. Approve, retain and correct
Route exceptions to a reviewer, document the resolution and retain the invoice and supporting records in the business’s accounting system. If a genuine correction is needed, follow the applicable tax-credit-note and correction rules instead of editing a supplier’s original invoice without an audit trail.
Timing and the e-invoicing distinction
The FTA’s published Taxable Person Guide states a general 14-calendar-day tax-invoice issuance rule from the date of supply, with special treatment for qualifying summary tax invoices. Determine the correct date of supply and consider any applicable exceptions before relying on a deadline.
A PDF emailed to a customer is not, by itself, a structured UAE e-invoice. The FTA’s UAE e-invoicing overview distinguishes structured electronic invoice data from PDFs, Word files and scanned images. Businesses should therefore review both their existing VAT invoice controls and their future electronic exchange capabilities; these are related but distinct workstreams.
What finance managers should implement this month
Assign an invoice-template owner; sample invoices from each sales channel; test full and simplified cases separately; document foreign-currency and reverse-charge exceptions; and add a monthly exception report. Track repeated supplier TRN errors, missing supply dates, incorrect VAT calculations and approvals delayed by incomplete supporting documents. This creates a measurable improvement programme rather than a one-off compliance exercise.
Clearer invoices. Stronger VAT controls.
Improve invoice accuracy, bookkeeping workflows and documentation reviews with practical support from VASS International.
VASS International · Dubai, UAE
Information reviewed 6 November 2026. This is a general operational guide, not a legal opinion; apply current legislation and FTA guidance to the facts of each transaction.