Estimated reading time: 5 min · Updated November 16, 2026
UAE corporate tax registration checklist preparation starts with one practical question: which registration timeline applies to your business? A newly incorporated UAE company, an older licence holder, a foreign-managed company and an individual carrying on business may face different rules. This guide helps founders and finance teams identify the right route, assemble evidence and reduce avoidable EmaraTax application errors.
UAE corporate tax registration checklist: determine your category first
The Federal Tax Authority’s registration timeline announcement explains that a UAE-incorporated resident juridical person established on or after 1 March 2024, including a Free Zone Person, generally has three months from incorporation, establishment or recognition to apply for Corporate Tax registration. This is a registration deadline, not a general tax-return filing deadline. The actual rule depends on legal status and facts; do not use it for every applicant.
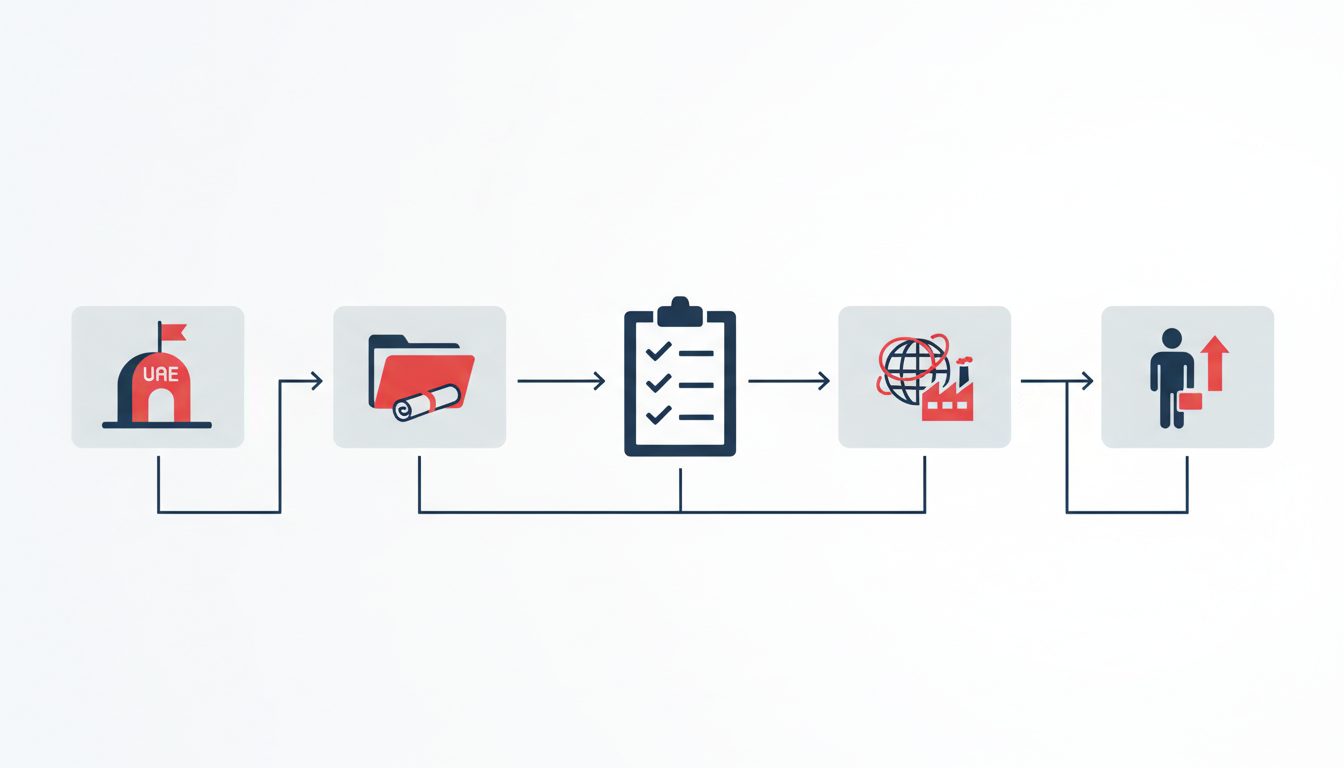
Visual 1 · Choose the applicable registration route
New UAE-incorporated resident juridical person (on/after 1 March 2024) → check three-month incorporation-based rule.
UAE resident juridical person established before 1 March 2024 → check the historical licence-month timetable, including earliest licence where relevant.
Foreign juridical person managed and controlled in UAE → examine the financial-year-based registration rule.
Non-resident with UAE permanent establishment or nexus; or natural person → apply the separate category-specific tests and timeframes.
For older UAE resident companies, the FTA’s public clarification explains the licence-month timetable and treatment of expired or multiple licences. A foreign juridical person effectively managed and controlled in the UAE may instead be subject to a three-month period after its financial year ends. Non-resident permanent establishments and nexus cases have separate rules. A natural person is not automatically treated as a company simply because they hold a business licence.
Documents to prepare before opening EmaraTax
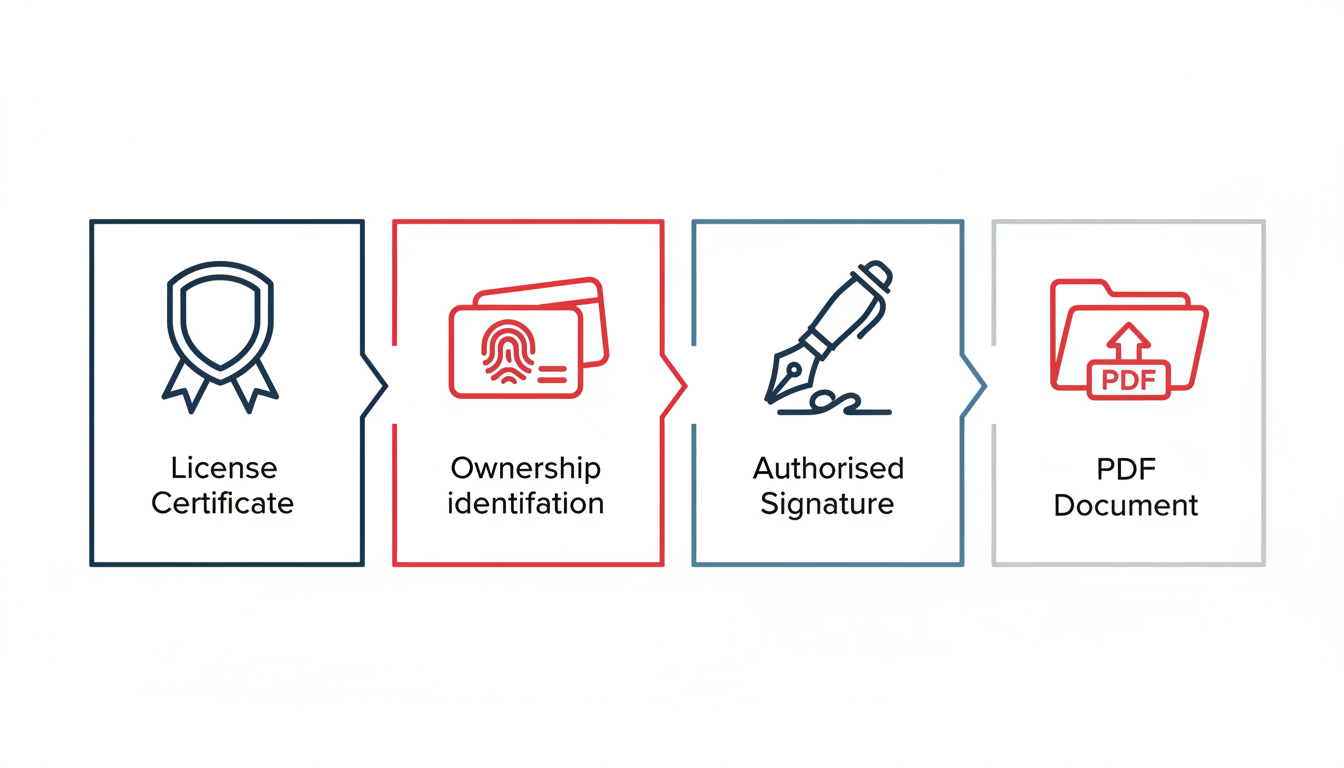
The FTA Corporate Tax Registration service identifies core supporting documents, including an incorporation or equivalent formation document where available, commercial registration, valid trade licence (including branch licences where relevant), identification for owners holding more than 25% and authorised signatories, and proof of signatory authorisation. Additional documents may be needed for particular legal categories. Check that the registered legal name, licence details and ownership records agree across the application.
Visual 2 · Application document control checklist
ENTITY — legal name, incorporation date, licence number, jurisdiction and entity type match the source documents.
OWNERSHIP — identify owners above the stated documentation threshold and collect required ID copies.
AUTHORITY — confirm the person submitting is authorised and retain evidence of that authority.
FILES — use readable PDF documents; the FTA service states a 15 MB maximum per document.
How to complete the Corporate Tax registration workflow
The FTA describes the following EmaraTax application process: activate an account, create or open the taxable-person profile, select Corporate Tax registration from the relevant actions menu, complete the application and submit it for review. Existing VAT registrants should check their current EmaraTax profile rather than creating inconsistent duplicate entity records.
Visual 3 · Pre-submission review workflow
1 · CLASSIFY → confirm resident/non-resident, juridical/natural person and any relevant Free Zone status.
2 · DATE → document the applicable registration rule and calculate the deadline from the correct trigger.
3 · VALIDATE → reconcile licence, ownership, contact and authorised-signatory records.
4 · SUBMIT → retain application acknowledgement, track FTA requests and archive the issued registration number.
Five avoidable registration mistakes
- Using a generic deadline: a three-month rule does not cover all persons and historic incorporation dates.
- Confusing registration with filing: the Corporate Tax return and payment deadlines are separate. For example, the FTA’s September 2026 notice describes the general nine-month period from the end of a taxable period for filing and payment, subject to applicable provisions.
- Ignoring multiple licences: historical resident-company rules may require reference to the earliest licence issuance date.
- Incomplete authorisation: a submission may stall if signatory authority is unclear.
- Assuming registration establishes a tax exemption: registration, exemption eligibility, tax computation and return obligations are distinct questions.
What if the deadline has already passed?
Do not assume an expired deadline makes registration unnecessary. Check the correct category, prepare the application promptly and assess the applicable administrative penalty and any available relief or waiver mechanism using current FTA guidance. The FTA’s March 2025 notice describes a AED 10,000 late-registration administrative penalty for natural persons required to register who miss their applicable deadline; this is not a substitute for reviewing current decisions and any relief conditions in an individual case.
A practical finance-team control after registration
Store the registration confirmation, tax registration number, relevant licence versions and deadline calculation together. Assign responsibility for reviewing changes to legal form, branch arrangements, accounting periods and ownership. Maintain a calendar for return filing and payment separately from registration. For businesses that need ongoing records support, see VASS International’s Accounting & Bookkeeping services.
VASS INTERNATIONAL · UAE TAX ADVISORY
Register with clarity, not guesswork.
Need help reviewing your Corporate Tax registration category, supporting documents or finance controls? Speak with VASS International.
Reviewed 8 November 2026. General information only; determine the applicable obligations from the legislation, FTA decisions and your specific facts. This article does not constitute a legal or tax opinion.