Estimated reading time: 7 min · Updated November 17, 2026
Executive summary
UAE e-invoicing is the regulated exchange of structured invoice data through Accredited Service Providers (ASPs), with electronic reporting to the Federal Tax Authority. It is not simply sending a PDF invoice by email.
- The voluntary programme began on 1 July 2026; mandatory onboarding is phased from January 2027.
- For in-scope businesses with annual revenue of AED 50 million or more, the revised ASP appointment deadline was 30 October 2026; implementation starts 1 January 2027.
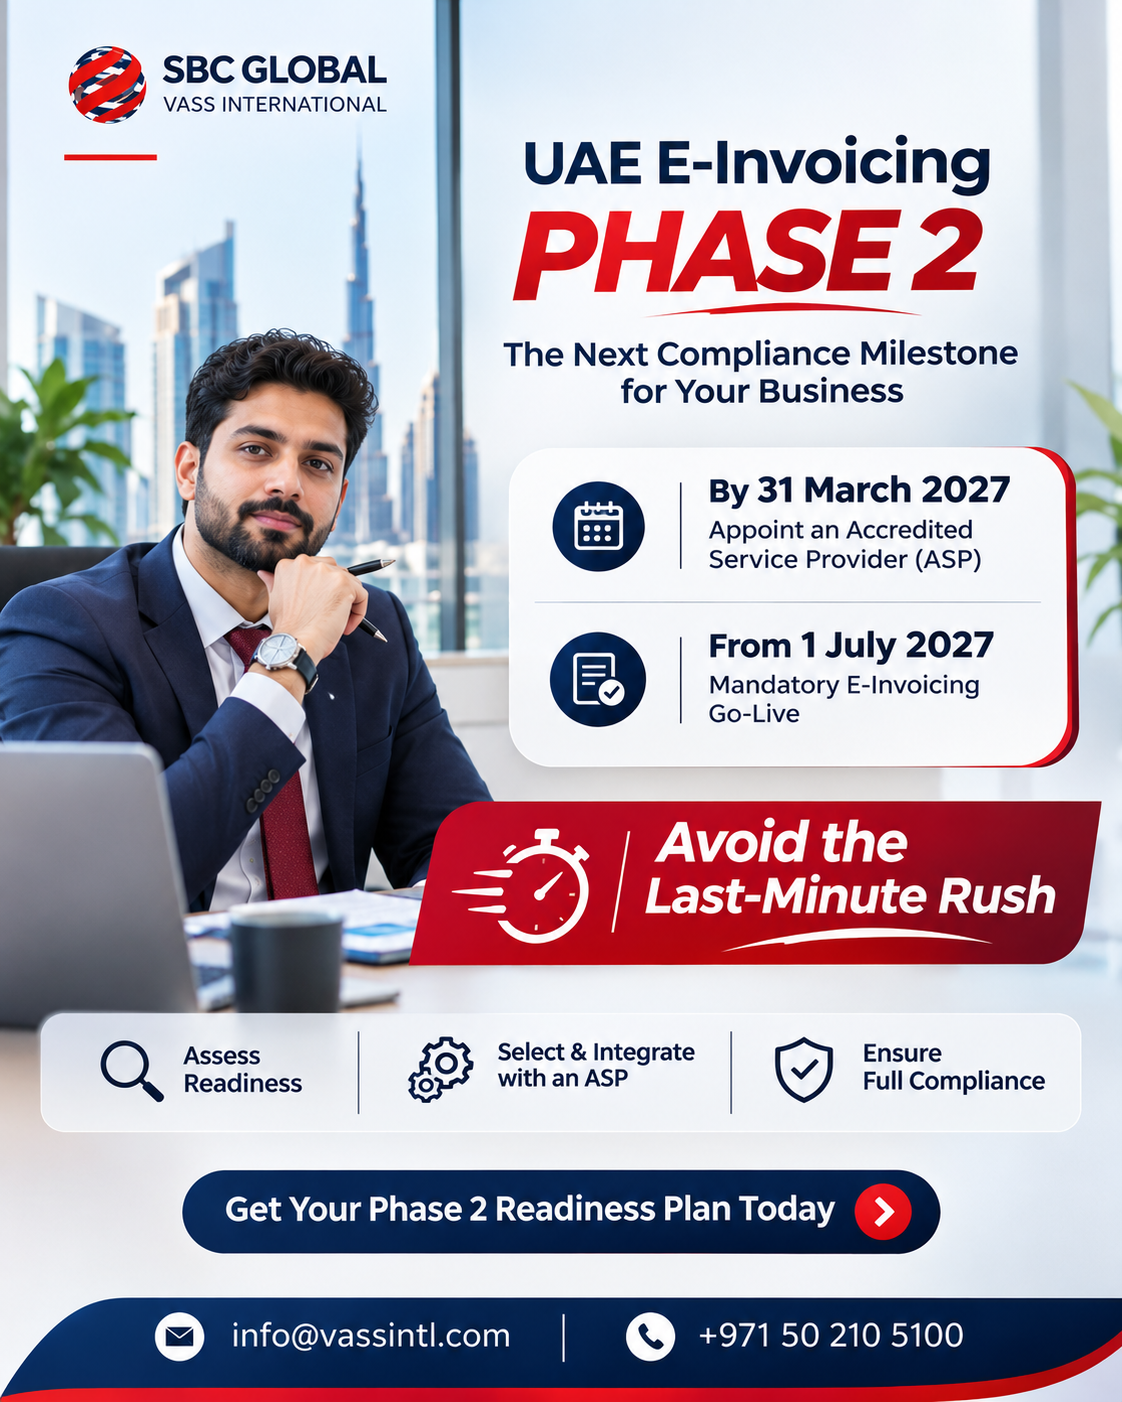
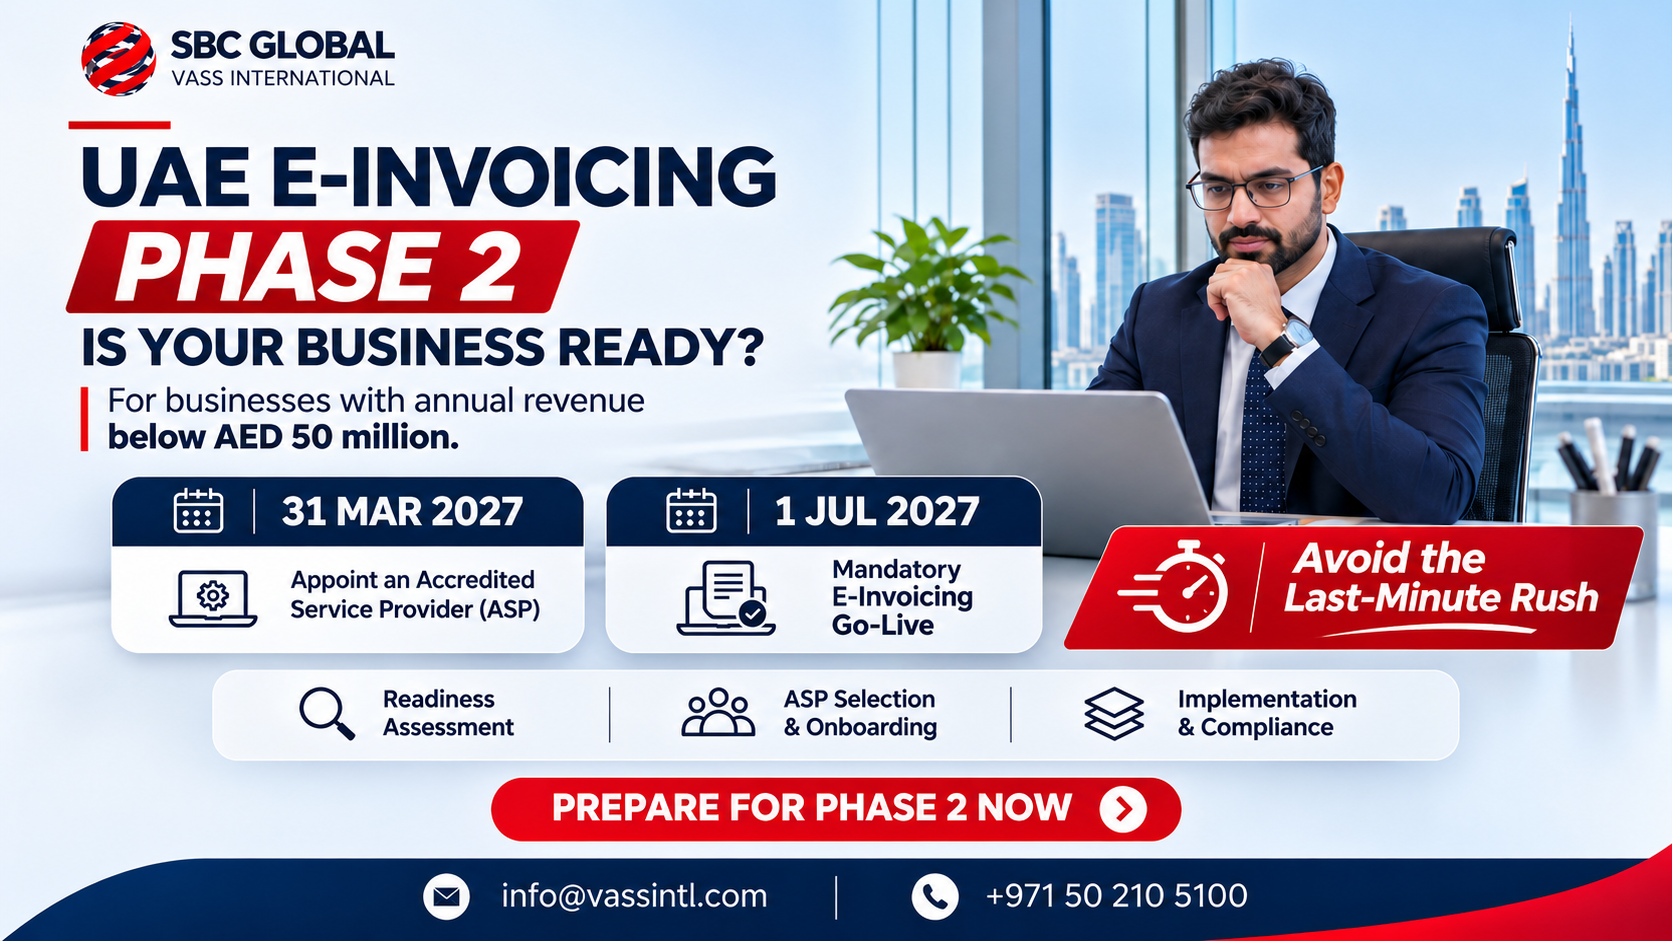
- For in-scope businesses below AED 50 million, the ASP deadline is 31 March 2027 and implementation date is 1 July 2027.
- Start with legal scope, clean master data, ERP readiness, supplier/customer information and documented exception handling.
Businesses across the UAE are preparing to replace isolated invoice PDFs and manual handoffs with a structured electronic exchange. For finance leaders, the largest challenge is rarely printing an invoice: it is ensuring the same transaction remains accurate from the ERP or accounting system through validation, transmission, tax reporting and reconciliation. This practical guide explains the scope, official deadlines, exchange architecture, provider selection and operational controls.
1. What counts as a UAE electronic invoice?
An electronic invoice under the UAE framework is structured invoice data issued, exchanged and reported in a prescribed electronic process. A scanned paper invoice, ordinary PDF attachment or manually emailed spreadsheet is not equivalent merely because it is digital. The Ministry of Finance (MoF) provides official mandatory-field requirements and guidelines, while an Accredited Service Provider (ASP) facilitates compliant exchange. Businesses remain responsible for the quality of their own transaction data and for determining their obligations.
Examples of fields to assess include the correct supplier and buyer identity, tax identifiers where applicable, invoice dates and references, line descriptions, quantities, tax classifications, totals, currencies and credit-note links. The exact applicable set must be validated against the current MoF specifications and an authorised ASP’s implementation guidance.
2. Official UAE e-invoicing rollout timeline
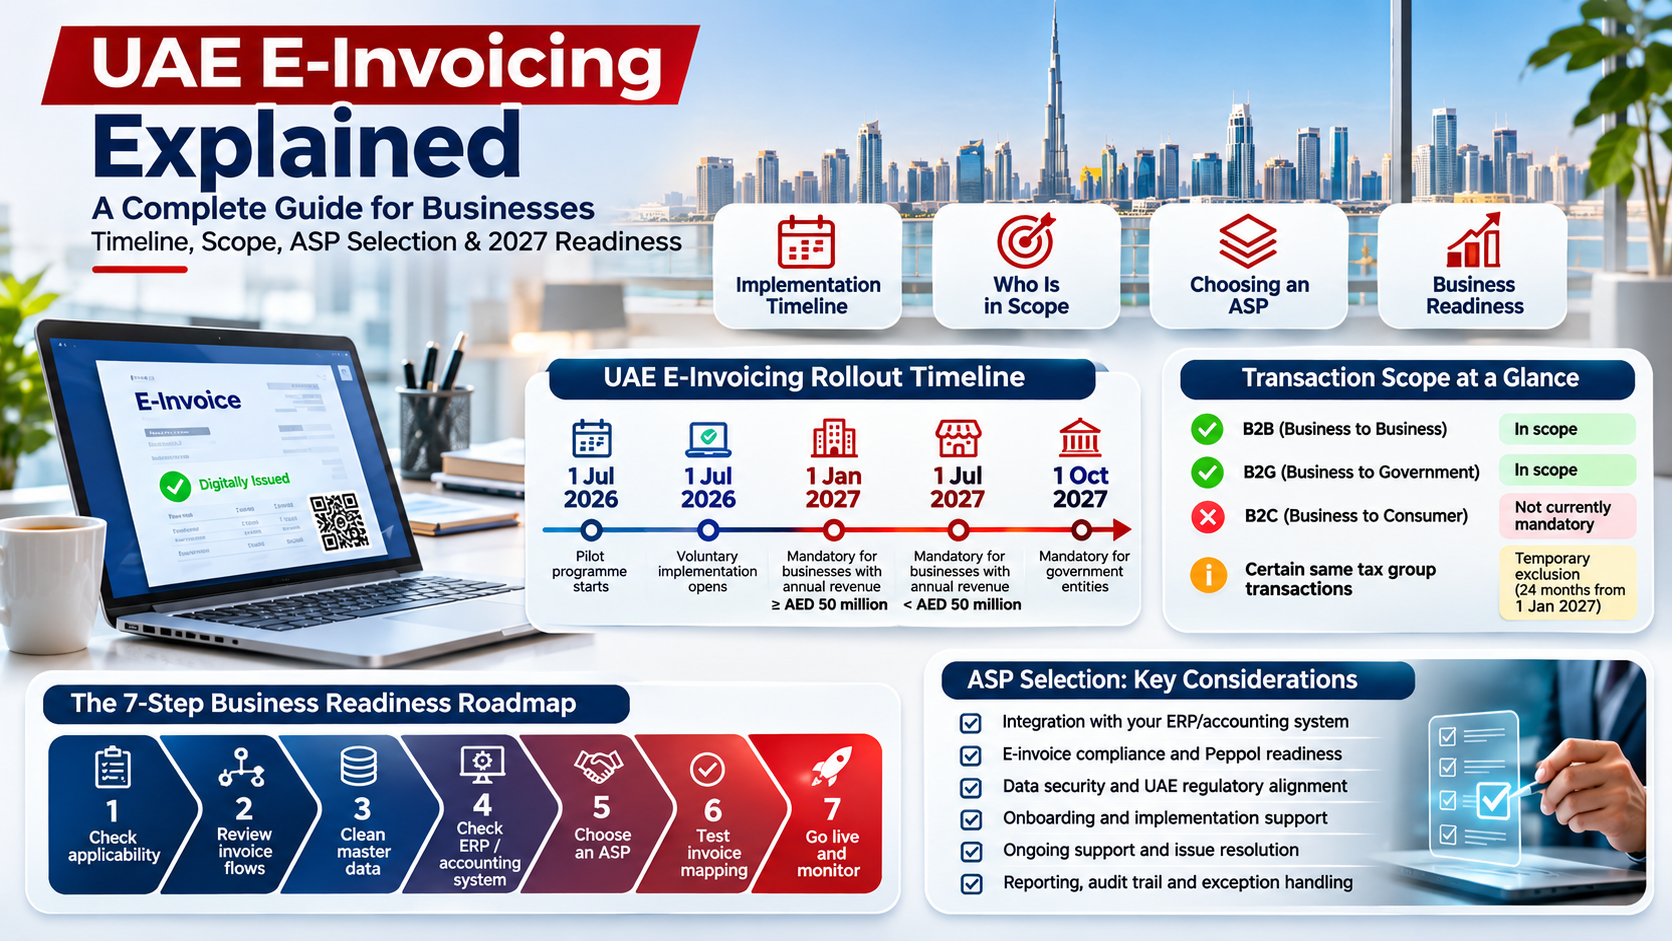
Graph 01 — Implementation and ASP deadlines
Chronological roadmap based on the Ministry of Finance’s amended rollout decisions. Bars are visual milestones, not a measure of adoption or market share.
What the dates mean: A company over the AED 50 million threshold should already have addressed ASP appointment by November 2026. Businesses below the threshold have more time, but should not postpone ERP discovery, transaction mapping or vendor evaluation until March 2027. The revenue bands determine a phase for in-scope entities; they do not themselves establish whether a particular transaction falls within the regime.
3. Which transactions are in scope?
Graph 02 — Transaction-scope decision matrix
In particular, voluntary adoption does not mean every transaction suddenly becomes compulsory in 2026. VAT registration status alone is also not a sufficient scope test. Businesses should map real sales and purchasing scenarios, cross-border cases, credit notes, intercompany transactions and any exemptions under the current decisions.
4. How the five-corner electronic invoice model works
Graph 03 — Simplified five-corner exchange
One reason the ASP decision matters is that the provider must support the required format, exchange workflow, status messages, error handling and operational evidence. A software vendor’s logo on a proposal is not a substitute for verifying the actual legal entity’s accreditation on the MoF’s official provider list.
5. Selecting an Accredited Service Provider
Start with the official Ministry of Finance eInvoicing portal and its currently accredited provider directory. Then evaluate providers using a documented shortlist, comparable demonstrations and signed responsibilities. The 2026 accreditation rules superseded previous arrangements; do not rely on outdated pre-approval marketing claims.
| Evaluation area | Questions finance and IT should ask | Evidence to request |
|---|---|---|
| Official accreditation | Is this exact provider legal entity accredited now? | Current listing in the MoF directory |
| ERP integration | Does it support the actual ERP, invoice types and credit-note scenarios? | Working integration demonstration and mapping specification |
| Validation | How are incomplete customer fields, invalid data and rejected documents handled? | Exception workflow, sample errors and support SLA |
| Security and continuity | How are data access, outages, incident escalation and recovery handled? | Security controls, support commitments and exit process |
| Total cost | What is charged for setup, integration, monthly use, volume changes and support? | Itemised proposal and written service scope |
A low subscription price is not automatically the least expensive implementation. Businesses should evaluate connector work, internal testing time, exception-resolution support, training, renewals and potential changes to transaction volumes.
6. ERP and outsourced accounting readiness
For VASS clients, the initial project should be a controlled finance-data review rather than a rushed software purchase. The chart below illustrates a practical seven-step workflow that can be coordinated with an internal finance owner and relevant technical specialists.
Graph 04 — Seven-step readiness workflow
Outsourced accounting can help maintain reconciled ledgers, reliable source documents and monthly reporting during the transition. However, business management must retain authority over transaction approvals, access controls and compliance decisions. VASS can coordinate readiness and accounting advisory; VASS does not present itself as an Accredited Service Provider. Any ASP relationship or technical delivery partner should be confirmed in the signed scope.
7. Common mistakes that create avoidable delays
- Starting with a logo or a PDF format: structured data quality and compliant routing matter more than visual invoice design.
- Not separating entity records: multiple VAT registrations, branches or group structures can complicate issuance and identification.
- Skipping credit-note tests: refunds, corrections and invoice references must be mapped and tested separately.
- Missing exception ownership: a rejected message needs a clear owner, cause, correction, revalidation and documented closure.
- Confusing tax reporting with invoice exchange: confirm how each status flows between seller, ASP, buyer and FTA reporting.
- Assuming old penalty references are current: the MoF announced Cabinet Decision No. 173 of 2026, replacing the earlier 2025 administrative penalty decision. Always check current law and applicable conditions.
8. A practical 30-day preparation plan
| Period | Recommended activities | Expected output |
|---|---|---|
| Days 1–7 | Confirm entities, scope, transactions, project owner and ERP inventory | Scope and responsibilities register |
| Days 8–14 | Check master data quality, mandatory fields and invoice/credit-note examples | Data-gap and field-mapping workbook |
| Days 15–21 | Shortlist accredited ASPs, request demonstrations and compare integration scope | Evidence-based ASP comparison |
| Days 22–30 | Plan testing, staff responsibilities, error response, reports and management approval | Implementation roadmap with accountable owners |
9. Official references and next steps
Use the following primary sources for regulations and updates. Dates, detailed fields and exclusions may change through subsequent legislation or Ministry publications:
- UAE Ministry of Finance — Official eInvoicing portal, guidelines, ASP list and legislation
- Ministry of Finance — Updated ASP deadline for the large-revenue phase
- Ministry of Finance — 2026 scope and data-storage amendments
- Ministry of Finance — Updated administrative penalties
For more detailed control testing, also read VASS’s nine ERP data-mapping errors and the finance-team readiness checklist.
Prepare your business for UAE e-invoicing with VASS
VASS International can help assess business-process readiness, outsourced accounting records, VAT treatment, master-data quality and documented ERP gaps, while coordinating technical questions with a duly accredited ASP under an agreed scope. Start with a practical gap review rather than assumptions about software or timelines.
Request an E-Invoicing Readiness Consultation
VASS International · Dubai, UAE · +971 50 210 5100 · info@vassintl.com